
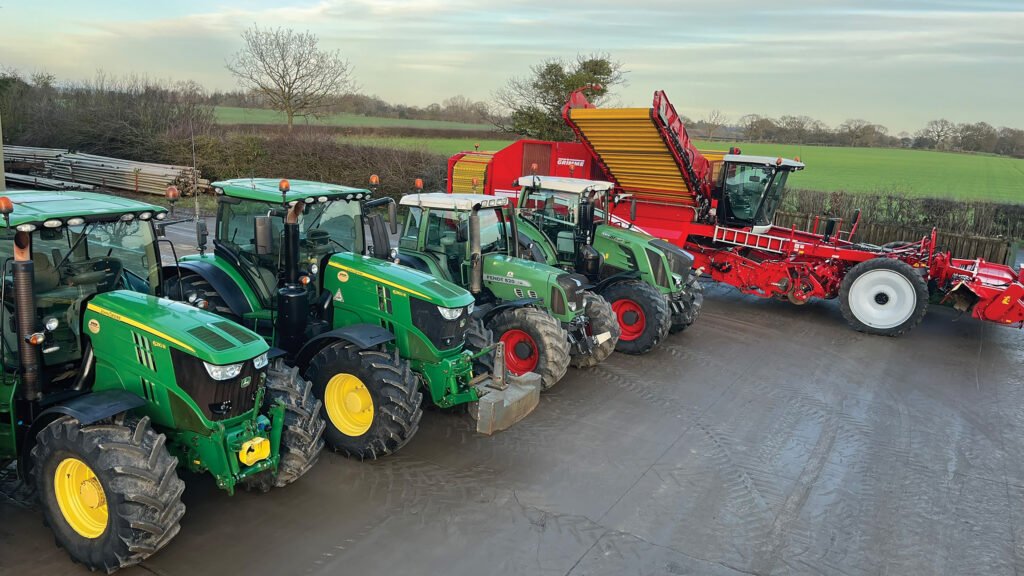
Tax is often overlooked when making decisions about machinery sales, but aligning the timing and various other factors can significantly improve your financial outcome.
Timing is critical, particularly for businesses in their final year of trading, as farmers’ averaging cannot be used to balance out profits and losses during that closing period, explains Kate Bell, a partner in the farms and landed estates team at accountant Albert Goodman.
“Sometimes it’s unavoidable that a sale happens in the final year of trading as the tax considerations, seasonal and commercial factors often don’t coincide,” says Kate.
However, advanced planning can be beneficial. For instance, a sale could be conducted in one trading year, followed by the use of contractors in the final year. This approach allows any profits or losses from the sale in the penultimate year to be included in income tax averaging.
Alternatively, selling the majority of machinery in one year while continuing to farm on a smaller scale for another year also permits an averaging claim in the penultimate trading year.
The interplay between different taxes—such as income or corporation tax and capital gains tax—must also be carefully considered. Because of this, you should consult your accountant early to ensure there is sufficient time to secure the best overall result.
Kate’s pre-machinery sale advice also includes:
Know what your tax pool is before selling. The written-down value of machinery might be low or even zero, but if capital allowances have been claimed, the sale proceeds are subject to tax at the taxpayer’s marginal income tax rate, which often comes as a shock after the sale. Businesses (partnerships) with a corporate partner may have a larger tax pool because the presence of a corporate partner means the Annual additional tax liability.
Investing in plant and machinery. Planning ahead for capital allowances is vital. Limited companies can utilize both the AIA and full expensing (FE), which allows 100% of qualifying expenditure on plant and machinery to be deducted for tax purposes in the year of purchase. FE is restricted to limited companies. Partnerships that include a corporate partner are ineligible for the AIA and should not assume that 100% tax relief will be available in the first year when evaluating investment decisions. The timing of a purchase, the date the asset is put into use, and the chosen finance method can all significantly influence the availability and timing of tax relief. Consequently, careful planning is essential to maximize these benefits.
VAT. Do not deregister before selling machinery and other equipment. Deregistering prior to the sale makes the seller personally liable for any VAT on the sale prices; for every £100,000 of income generated from the sale, £20,000 would be owed in VAT.
Business asset disposal relief. This can reduce the Capital Gains Tax rate from 24% to 18% on qualifying business assets sold upon the disposal or cessation of a business from 6 April 2026, subject to a lifetime limit of £1m in qualifying gains.
Review business structure. This should be completed well in advance of any sale to allow sufficient time for potential adjustments to achieve a better tax outcome, without inadvertently violating anti-avoidance rules, which could result in an unexpected tax bill.
Live- and deadstock sales tax considerations
Stock values. While live- and deadstock values might appear low in the closing valuation, seasonal fluctuations can lead to a higher-than-expected income tax bill when stocks are sold for amounts exceeding those book values.
A relevant example this year is forage stocks, which are generally worth more than their production cost due to current shortages.
Herd basis. An election for the herd basis offers the advantage that any profit or loss on the disposal of the herd, or a significant portion (exceeding 20%) of the animals, is not taxable.
Only animals kept primarily for the products they provide, or in the case of breeding animals for their offspring, are eligible for a herd-basis election, at which point they are treated as capital assets.
Eligible herds include suckler beef or dairy herds, breeding flocks, laying hens, sheep kept for wool production, and horses kept for breeding.
Strict HMRC regulations govern when a herd basis election may be made.
