
The FTSE 100 finished Wednesday’s session virtually unchanged, as positive US economic data was balanced out by growing concerns regarding the stability of the Middle East.
In London, the FTSE 100 index closed slightly lower at 10,705.26. The FTSE 250 dropped 164.87 points, or 0.7%, to 24,361.58, while the AIM all-share index declined by 2.40 points, or 0.3%, to 793.44.
European markets also saw losses on Wednesday, with the CAC 40 in Paris sliding 0.4% and the DAX 40 in Frankfurt retreating 0.7%.
In New York, the Dow Jones Industrial Average was down 0.5% as the London market closed. The S&P 500 fell 0.6%, and the Nasdaq Composite dropped 0.9%.
London markets saw a mid-afternoon rally following a report indicating that US business activity growth had accelerated for the fourth consecutive month in September, reaching its highest level in over five years.
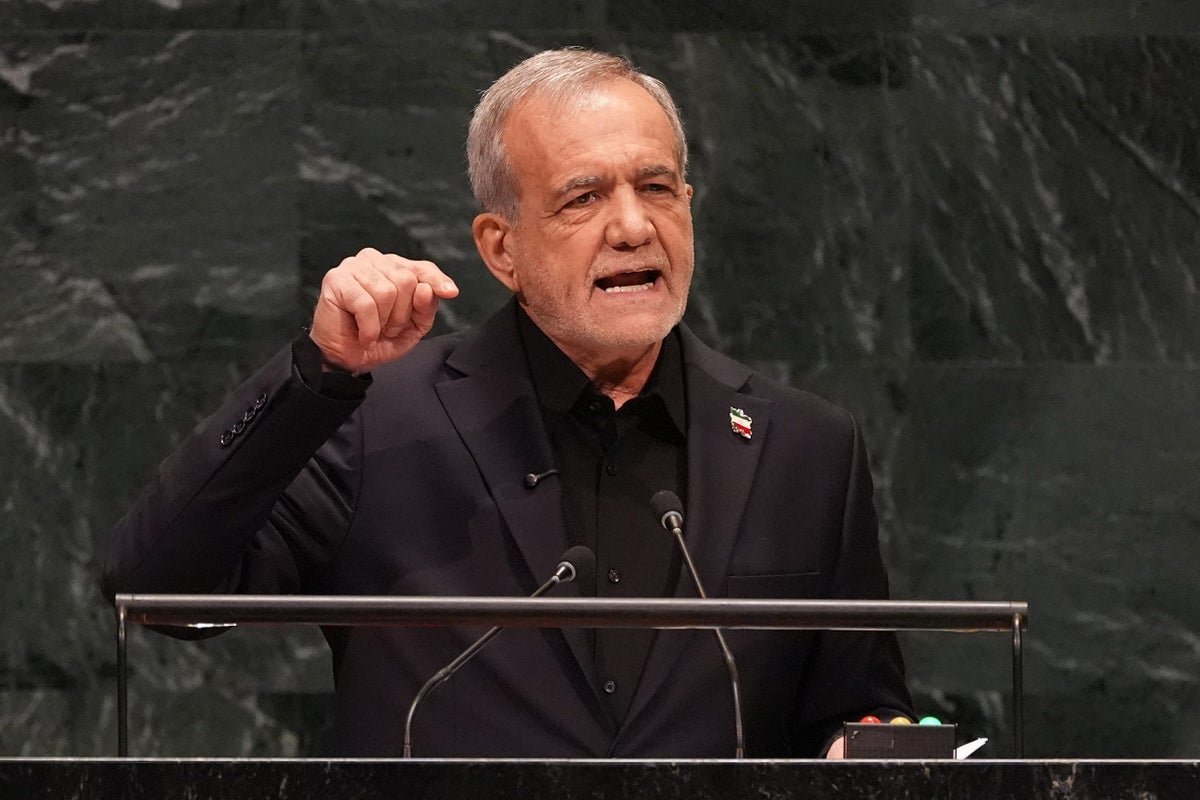
However, these gains proved temporary as Iran’s President Masoud Pezeshkian delivered a defiant speech at the United Nations.
S&P Global’s “flash” US composite PMI output index climbed to 58.4 in September, up from 56.0 in August. This 62-month high surpassed the consensus forecast of 55.3 cited by MNI.
S&P Global noted that a continued surge in service sector activity was bolstered by a renewed uptick in manufacturing output.
Chris Williamson, chief business economist at S&P Global Market Intelligence, stated that historical trends suggest the latest survey data points to an annualised growth rate of approximately 5%, with a 4% gain now projected for the third quarter overall.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the Covid-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and approach from Ember Infrastructure Management.
The top performers on the FTSE 100 were BP, up 13.10p at 555.55p, Babcock International, up 22.60p at 999.50p, Relx, up 50.00p at 2,500.00p, BAE Systems, up 37.00p at 2,029.50p and Ithaca Energy, up 4.80p at 289.30p.
The biggest decliners on the FTSE 100 were JD Sports Fashion, down 4.72p at 74.01p, Fresnillo, down 128.50p at 2,864.50p, Autotrader, down 20.10p at 464.05p, Antofagasta, down 143.00p at 3,700.00p and Endeavour Mining, down 155.00p at 4,565.00p.
Thursday’s local corporate calendar features a trading statement from Halma, half-year results from Vistry and Raspberry Pi, and full-year figures from DFS Furniture.
Thursday’s global economic calendar includes the Ifo business climate report in Germany and interest rate decisions from central banks in Norway, Sweden and Switzerland.
In the US, data regarding weekly jobless claims, new home sales, and building permits will be released.
